One of the most common questions people have when considering bankruptcy is also one of the most understandable:
How much money can I have in my bank account when I file bankruptcy?
The short answer is that there is no universal dollar amount that automatically determines whether you can keep the money in your checking or savings account. What happens to the money in your bank account depends on several factors, including the type of bankruptcy you file, how much money is in the account when you file, where the money came from, and which bankruptcy exemptions apply to your situation.
For Maryland residents, understanding the state’s bankruptcy exemptions is especially important because Maryland has opted out of the federal bankruptcy exemption system. Maryland bankruptcy filers generally must use the exemptions provided under Maryland law rather than the federal exemption list.
Your Bank Account Is an Asset in Bankruptcy
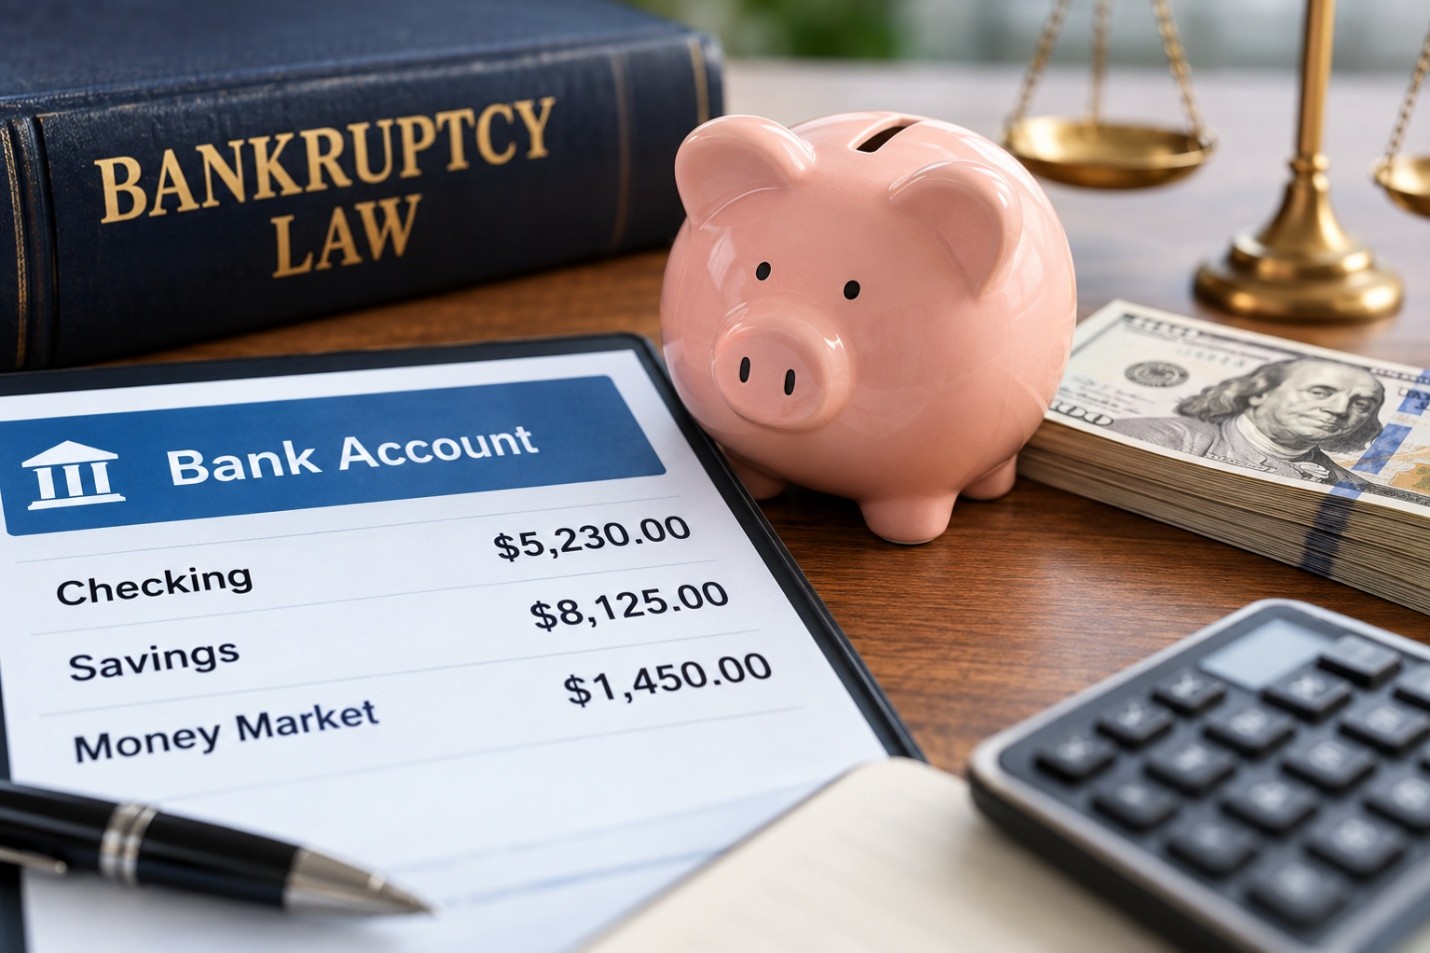
When you file bankruptcy, you are required to disclose your assets. This includes money in checking accounts, savings accounts, money market accounts, and other financial accounts.
In a Chapter 7 bankruptcy, your assets generally become part of the bankruptcy estate, subject to your right to claim applicable exemptions. That does not mean that you automatically lose the money in your bank account. Instead, the important question is whether the money can be protected under an available exemption.
This is why simply asking, “Can I have $5,000 in my bank account and still file bankruptcy?” does not tell the whole story.
Two people could have the same amount of money in their accounts but have very different outcomes depending on the source of the money and the exemptions available to each person.
How Much Money Can You Keep?
There isn’t a simple “bank account limit” for someone filing bankruptcy in Maryland.
For example, having $2,000 in a checking account does not automatically mean that the money will be taken. Likewise, having $10,000 does not automatically mean that you will lose $10,000.
The analysis involves looking at the money as part of your overall assets and determining what exemptions may be available to protect it.
Maryland law provides exemptions that can potentially protect certain property and money. One important exemption allows a debtor to elect to exempt up to $6,000 in property under Maryland law, subject to the requirements and limitations of the applicable statute. Maryland Courts also explain that certain types of funds may qualify for separate exemptions depending on their source, including certain retirement benefits, Social Security benefits, workers’ compensation, unemployment benefits, and other protected funds.
The specific exemption available to you—and how it applies in a bankruptcy case—is something that should be reviewed with a bankruptcy attorney before filing.
The Source of the Money Matters
Not all money in a bank account is treated the same way.
For example, money received from certain government benefits may have protections that do not apply to ordinary wages or savings. Similarly, money held in a qualified retirement account may be treated differently from money sitting in a regular checking account.
This is one reason it is important to be completely transparent about your finances when discussing bankruptcy with an attorney.
You should be prepared to explain:
- How much money is currently in each bank account
- Where the money came from
- Whether you recently received a tax refund, inheritance, bonus, settlement, or other large payment
- Whether you recently transferred money to another person
- Whether you have other financial accounts
- Whether you own other assets that may affect your available exemptions
Trying to move or hide money before filing bankruptcy can create serious problems. Bankruptcy requires full disclosure of your assets and financial information.
What If My Paycheck Is in My Account?
Many people worry because their normal paycheck is deposited into their checking account shortly before they file bankruptcy.
A paycheck sitting in a bank account is generally part of the financial picture that must be disclosed. However, that does not necessarily mean you will lose the money.
The amount in the account on the date of filing, the nature of the funds, your household circumstances, and the exemptions available to you can all affect the analysis.
Timing can also matter. For that reason, if you are considering bankruptcy and have recently received—or are about to receive—a large paycheck, bonus, tax refund, settlement, inheritance, or other payment, it is a good idea to discuss it with your bankruptcy attorney before filing.
What About Chapter 7 Bankruptcy?
Chapter 7 is often called a “liquidation” bankruptcy, but that does not mean everything you own is automatically sold.
In Chapter 7, a bankruptcy trustee reviews the debtor’s assets and exemptions. If an asset is fully protected by an applicable exemption, the debtor generally gets to keep it. If an asset has nonexempt value, the trustee may have the ability to administer that asset for the benefit of creditors.
That is why the amount of money in your bank account on the day you file can be important.
For someone with significant cash in the bank, it is particularly important to understand the exemption analysis before filing rather than assuming that the money will be protected automatically.
What About Chapter 13 Bankruptcy?
Chapter 13 bankruptcy works differently.
Rather than liquidating assets in the same manner as a Chapter 7 case, Chapter 13 generally involves a repayment plan lasting several years. Your assets and exemptions can still be important because they can affect the amount that must be paid to unsecured creditors through the plan.
Having money in a bank account does not necessarily prevent someone from filing Chapter 13.
However, the amount of money you have and the nature of that money should be disclosed and considered when developing your bankruptcy strategy.
Don’t Empty Your Bank Account Before Filing
If you’re worried about losing money in your bank account, you may be tempted to withdraw the money, transfer it to someone else, or spend it before filing.
Do not make major financial moves simply to try to hide assets from the bankruptcy process.
Bankruptcy trustees can review financial records, and bankruptcy requires you to disclose your assets and financial transactions. Transferring or concealing assets can create substantially more serious problems than simply having money in a bank account.
Instead, talk with an experienced bankruptcy attorney about your options before making significant changes to your finances.
What Should I Do Before Filing Bankruptcy?
If you are considering bankruptcy, gather information about all of your financial accounts and assets before meeting with your attorney.
Bring or have available:
- Recent bank statements
- Savings account statements
- Retirement account information
- Recent pay stubs
- Tax returns
- Information about investments
- Information about any recent large deposits
- Information about inheritances, settlements, or other payments
- A list of your debts and monthly expenses
Your attorney can then evaluate your financial situation and determine which exemptions may apply.
So, How Much Can You Have in the Bank?
The answer is it depends.
There is no one-size-fits-all bank account balance that applies to every Maryland bankruptcy case. A person with several thousand dollars in a bank account may be able to protect some or all of it depending on the applicable exemptions and circumstances. Another person with the same balance could have a different result because of other assets, the source of the money, or other factors.
The most important thing is to understand your exemptions before you file.
If you are considering bankruptcy in Maryland, the Law Offices of Adam M. Freiman, P.C. can review your financial circumstances, explain how bankruptcy exemptions may apply to your assets, and help you understand your options.
Do not assume that you have too much money in the bank to file bankruptcy – and don’t assume that your money is automatically protected. Get professional advice before making important financial decisions.
This article is for general informational purposes only and is not legal advice. Bankruptcy laws and exemptions can be complex, and the application of exemptions depends on the facts of each individual case.